What will the Fed rate be at the end of 2026?
The conditions, incentives and evidence that could shape the answer.The apparent conflict between 4.1% and 4.25%
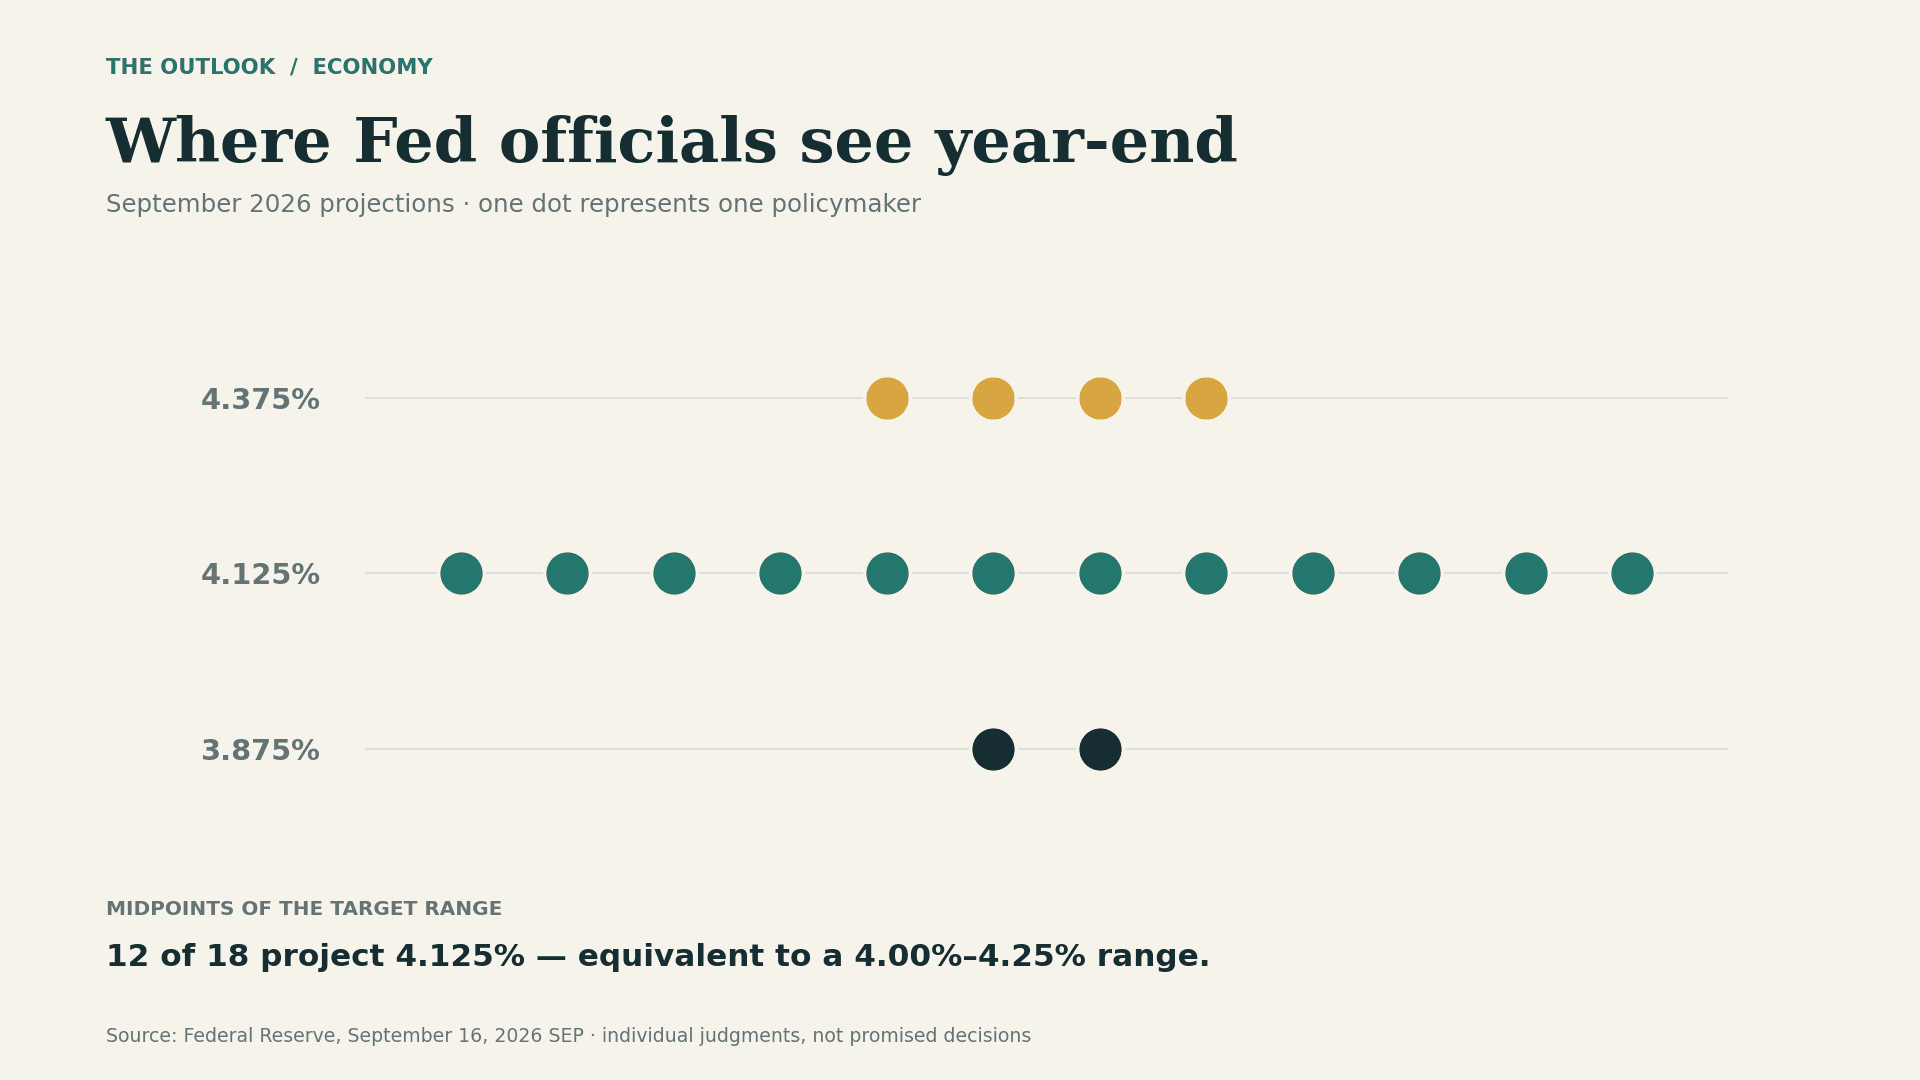
Two numbers can look inconsistent while describing the same thing. The September Summary of Economic Projections reports a 4.1% median for the federal funds rate at year-end. Its detailed distribution places the median at a 4.125% midpoint. A target range of 4.00%–4.25% has that midpoint. [2] The market asks for the upper bound, so the comparable outcome is 4.25%.
This is more than a rounding curiosity. A reader comparing the rounded projection directly with market labels might conclude that neither supports the other. First align the quantity being measured: lower bound, upper bound, midpoint, or an observed overnight rate. Only then compare the forecasts. Otherwise an apparent disagreement may be a difference in definitions.
The current target range after September’s increase is 3.75%–4.00%. [3] Moving from that upper bound to 4.25% requires a net increase of 25 basis points by the relevant December decision. That is arithmetic, not a prediction that a particular meeting must deliver the increase. The timing and the final level remain separate questions.
The dots show conditional judgments, not a binding vote
The detailed September distribution has 12 participants at a 4.125% year-end midpoint, four at 4.375%, and two at 3.875%. [2] Expressed as ordinary quarter-point target ranges, these correspond to upper bounds of 4.25%, 4.50% and 4.00%. This helps explain the menu of plausible levels without converting a collection of individual judgments into a guaranteed outcome.
Each projection is conditioned on the participant’s assessment of appropriate policy and the economy. The Fed itself emphasizes uncertainty in these paths. [2] A projection is not a contract with households, investors or other committee members. Treat it as evidence of how officials viewed the situation when it was prepared, then test that view against subsequent developments.
Nor should the fraction of dots at a level be read as the probability of that level. Participants can share assumptions, respond to the same new evidence and change their assessments together. The dots offer a useful map of disagreement; they are not independent lottery tickets. Our interpretation is that their value lies in revealing which policy paths need less or more revision from the September starting point.
Three routes to December, with different economic meanings
One path is a hold followed by a later increase. Another is an earlier increase followed by a hold. Both can land on the same upper bound. A third path is no further increase at all. The official calendar lists October 27–28 and December 8–9 as the remaining scheduled meetings. [4] Forecasting the destination does not require claiming certainty about each step.
The deciding evidence is unlikely to be one number. August core PCE inflation was 3.0% over a year earlier, while September unemployment was 4.2%. [5][6] These observations concern different months and different parts of the economy. A convincing year-end forecast should explain how the combination evolves, rather than select whichever release supports its preferred rate.
Consider the direction of a revision. Stronger inflation evidence alongside resilient activity would strengthen the higher-rate scenarios. A clearer slowdown with improving inflation would strengthen the unchanged or lower-rate paths. These are conditional comparisons. Calling the Fed “hawkish” or “dovish” adds little unless the label is tied to a specific observable change and the resulting policy arithmetic.
The deadline is narrower than the headline sounds
The market normally uses the upper bound announced after the December FOMC meeting and can resolve as soon as that decision is available. Only if no December decision has appeared by December 31 at 11:59 p.m. Eastern does its fallback use the upper bound then. [1] Someone expecting a late-December surprise must therefore read the operative rule carefully.
At the October 4 observation, the 4.25% outcome was priced at 48.05%, versus 27.8% for 4.00% and 11.05% for at least 4.50%. [1] A leading outcome below 50% is not a contradiction: several alternatives can divide the rest of the uncertainty. These prices do not supply our own probability estimate or establish that any contract is mispriced.
The practical approach is to maintain two separate notes: the rate path implied by the latest evidence, and the exact number the contract will measure. Update the first when substantive information changes. Keep the second anchored to the written rule. That prevents a broadly correct economic forecast from becoming an incorrect interpretation of the specific outcome. A forecast should be revised because its evidence changed, not because a different rounding convention briefly made the published numbers appear inconsistent.
WEIGH BOTH SIDES
What would change the outlook?
4.25%
Quoted market evidence: Oct 4, 2026, 09:57 UTC. The live market panel may show a newer observation.
A net quarter-point increase from today’s 4.00% upper bound would match this outcome; it also corresponds to the median September midpoint projection. [2][3]
No further increase or more than a quarter-point net increase would land in a different bracket. A changed outlook can overturn the September assessment.
The next signals to watch
The preserved October 4 quote for 4.25% was 48.05%. It was the leading listed outcome, while still below an outright majority probability. [1]
Compare identical definitions before judging disagreement. The projection makes this path understandable, but it does not prove an advantage at the market price.
A FEW GOOD QUESTIONS
What else should you know?
Why does the Fed say 4.1% while the market lists 4.25%?
The Fed summary rounds the projected midpoint. A 4.125% midpoint belongs to a 4.00%–4.25% range; the contract uses its upper bound. [1][2]
Is the dot plot a promise about future rates?
No. It records participants’ conditional assessments of appropriate policy, which can change as the economy changes. [2]
Does this contract always wait until December 31?
No. It normally resolves from the December meeting decision; December 31 is the deadline for its missing-decision fallback. [1]
CHECK THE EVIDENCE
Sources & further reading
- Polymarket: end-of-2026 Fed rate and resolution rules ↗polymarket.com
- Federal Reserve: September 2026 economic projections and individual rate assessments ↗federalreserve.gov
- Federal Reserve: September 16, 2026 policy decision ↗federalreserve.gov
- Federal Reserve: 2026 meeting calendar ↗federalreserve.gov
- BEA: August 2026 Personal Income and Outlays ↗bea.gov
- BLS: September 2026 Employment Situation, released October 2 ↗bls.gov
Published . AI-assisted, source-linked analysis. We distinguish evidence from interpretation; this article does not establish a trading edge. How we work →