How many Fed rate cuts in 2026?
The conditions, incentives and evidence that could shape the answer.The 2026 rate-cut story has changed
The useful starting point is the policy record. The Federal Reserve’s published table shows no reductions in 2026 and a 25-basis-point increase effective September 17. [2] That makes an article built around when an expected cutting cycle begins incomplete: the central bank has already moved in the opposite direction. Expectations from earlier in the year should be treated as old forecasts, not current guidance.
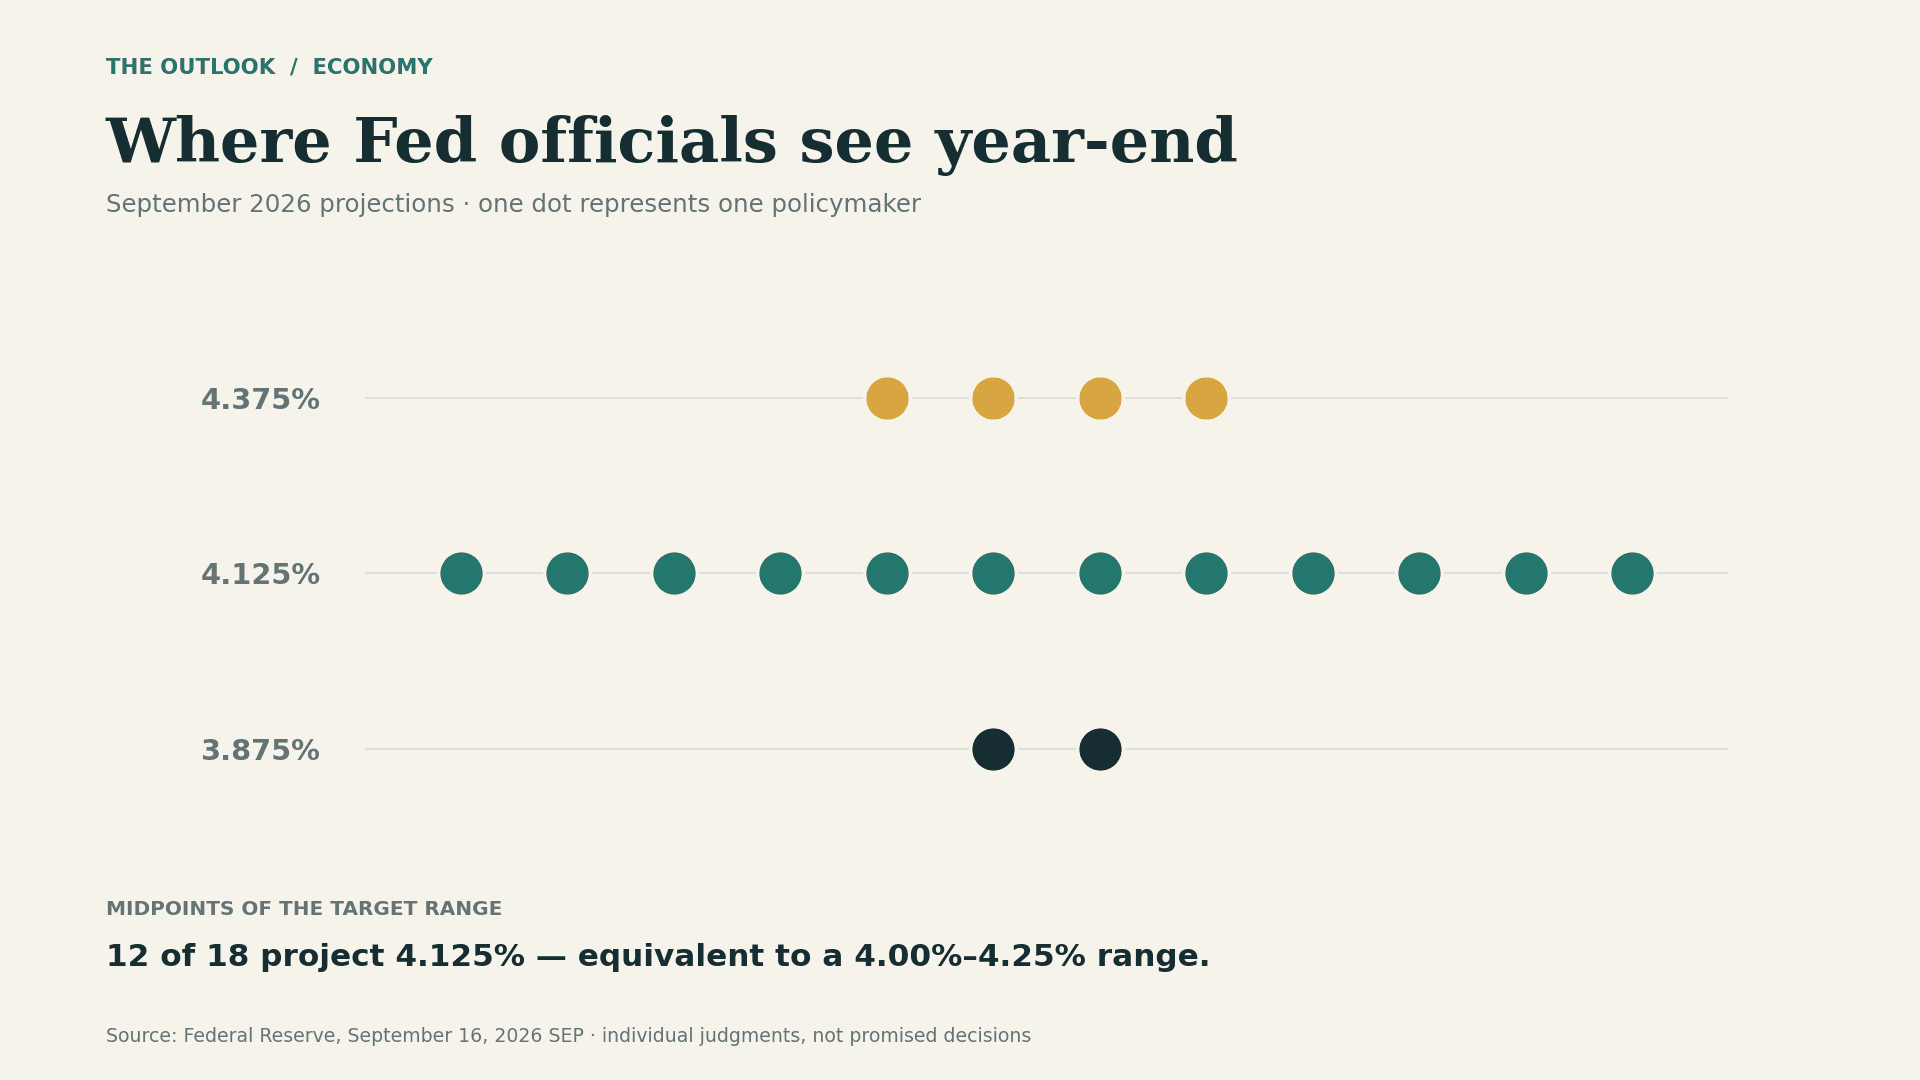
The September 16 statement put the target range at 3.75%–4.00% and emphasized inflation alongside resilient economic activity. [3] Our interpretation is that officials would need a changed assessment of the economy before reversing that action. This is a hurdle for a cut, not a promise never to cut. A committee can revise its position when new evidence warrants it.
For a household or business, the relevant planning question is therefore broader than the number of meetings left: what would make policy become less restrictive? Waiting for a calendar date is not an explanation. Looking for a sustained change in inflation, employment and demand creates a more useful framework, even for readers who never consider a prediction-market position.
Inflation and employment are pulling on different parts of the argument
BEA’s August release shows annual PCE inflation of 3.4%, with the measure excluding food and energy at 3.0%. [4] These are observed price changes, not a prediction of the next decision. Our reading is that continued inflation pressure weakens the argument for near-term easing, particularly if consumers and businesses can still sustain spending.
The October 2 jobs release adds a competing consideration: September payrolls rose by 29,000 and unemployment was 4.2%. [5] Slower hiring deserves attention, but one monthly estimate cannot establish a rapidly worsening labor market. Compare subsequent revisions and unemployment with the headline payroll number rather than treating every softer release as an automatic instruction to cut.
The two policy errors have different costs. Cutting too quickly could leave inflation pressure insufficiently restrained; holding tight while employment deteriorates could deepen the slowdown. This is our scenario framework, not a claim about officials’ private motives. The strongest case for a reversal combines clearer disinflation with weakness broad enough that waiting becomes harder to justify.
Three paths that readers should keep separate
First, the Fed could pause additional increases while making no cuts. That is entirely consistent with judging policy restrictive enough for the moment. Second, it could ease modestly after the evidence changes. Third, an abrupt deterioration could require a larger response. These are conditional paths; none follows mechanically from a single jobs number or a short-lived market rally.
The count and the year-end level answer different questions. In a hypothetical year containing one 25-basis-point hike and one 25-basis-point cut, the rate returns to its starting point, yet a cut still happened. A net-change chart would miss that distinction. Likewise, one 50-basis-point reduction is one policy decision but counts as two 25-basis-point units in this market. [1]
This matters most when a confident no-cut view is challenged. A small reduction would be enough to defeat a zero-cut outcome; a larger reduction can also remove lower exact-count brackets at once. The opposing case does not have to predict many routine cuts. It can instead rest on a single sufficiently important event before the time window closes.
The remaining calendar and the market’s narrower test
The scheduled decisions still ahead are October 27–28 and December 8–9. [6] Keep an evidence diary: what changed in inflation, what changed in employment, and whether official communication connects those changes to a different policy stance. Distinguish evidence favoring a pause in hikes from evidence favoring an actual reduction.
Our October 4 market snapshot priced the zero-cut contract at 95.95%. [1] That is a demanding expectation: the market was assigning little room to any qualifying cut. Agreeing that zero cuts is the most likely result does not establish that this particular quote offers an advantage. The relevant uncertainty is what could still happen during the entire remaining window.
Resolution includes scheduled and emergency reductions through December 31 at 11:59 p.m. Eastern. [1] A quiet December meeting does not end that exposure. The responsible conclusion is clear but conditional: zero cuts describes the record so far and a plausible continuation; a verified deterioration could still change the policy path before the year is over. A useful update should identify the new evidence that changed that assessment, rather than merely repeat the latest price or present yesterday’s reasoning with a new date.
WEIGH BOTH SIDES
What would change the outlook?
0 (0 bps)
Quoted market evidence: Oct 4, 2026, 09:57 UTC. The live market panel may show a newer observation.
If inflation pressure persists without a broad employment deterioration, maintaining or raising rates would leave the zero-cut outcome intact.
A material deterioration could prompt even one reduction before year-end, which would defeat zero cuts.
The next signals to watch
The preserved October 4 snapshot was 95.95% for zero cuts; this is an observed price, not our estimated fair probability. [1]
The observed record supports taking no cuts seriously. A high probability still requires evaluating the remaining downside scenarios and current price.
A FEW GOOD QUESTIONS
What else should you know?
How many times has the Fed cut rates in 2026?
None through the October 4 review. The official 2026 change table instead records a 25-basis-point increase in September. [2]
Does keeping rates unchanged count as a cut?
No. A hold leaves the target range unchanged. This contract counts actual reductions, including qualifying emergency actions. [1]
Can rates finish higher even if the Fed cuts once?
Yes. If increases exceed reductions, the year-end level can be higher despite a cut during the year. The count and the final level are different measurements.
CHECK THE EVIDENCE
Sources & further reading
- Polymarket: 2026 Fed rate-cut count and rules ↗polymarket.com
- Federal Reserve: changes in the federal funds target range ↗federalreserve.gov
- Federal Reserve: September 16, 2026 policy decision ↗federalreserve.gov
- BEA: August 2026 Personal Income and Outlays ↗bea.gov
- BLS: September 2026 Employment Situation, released October 2 ↗bls.gov
- Federal Reserve: 2026 meeting calendar ↗federalreserve.gov
Published . AI-assisted, source-linked analysis. We distinguish evidence from interpretation; this article does not establish a trading edge. How we work →